The next step after knowing how much money you can expect each month is to plan for your income when you retire. A Single Premium Immediate Annuity can convert a single lump sum into a steady, consistent cash flow, and in certain instances, can start within just a few months from the date of purchase.
It can give you a guaranteed retirement income and, in some cases, a guaranteed lifetime income during your lifetime.
What Is a Single Premium Immediate Annuity?
An annuity that receives one lump-sum payment is called a Single Premium Immediate Annuity. The insurance company will, in turn, pay the owner a regular income according to the contractual terms.
The payment may vary depending on your age, premium, payout option, interest rates and if payments are made for life or a fixed term. An immediate annuity may start payments within a relatively short time period following the purchase.
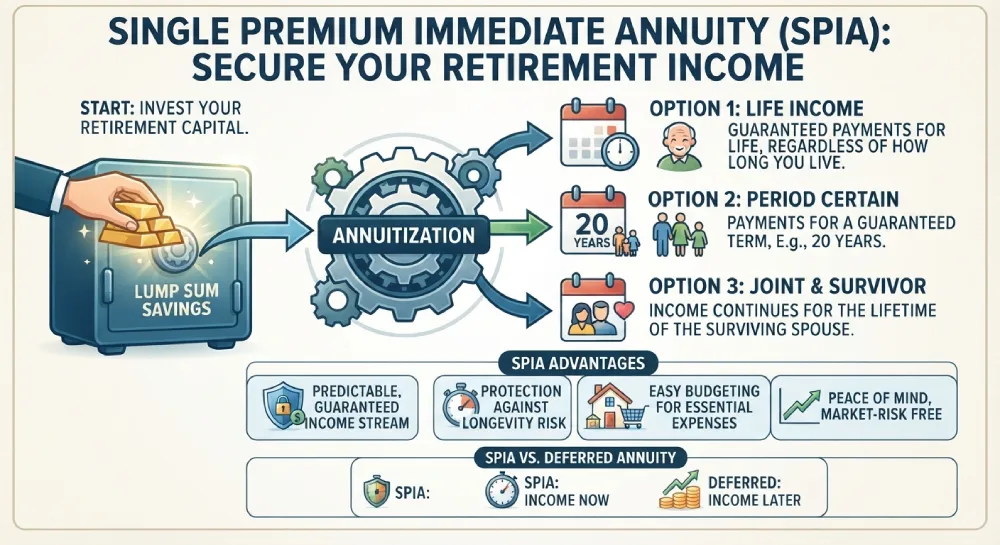
The practice of breaking down the lump sum into payments is known as annuitization. After players have made their selection, it is usually hard and sometimes not possible to alter the pay-outs, so it’s crucial for players to know what the contract offers prior to buying.
How Does a Single Premium Immediate Annuity Compare With Other Options?
A Single Premium Immediate Annuity is different from accumulation-focused products. A Deferred Income Annuity will pay an income sometime in the future and a Multi Year Guaranteed Annuity will usually guarantee a fixed interest rate for a number of years, as opposed to the premiums being converted into income payments right away.
Another comparison investors can make is between SPIA and MYGA to choose between immediate income and interest accumulation. Likewise, dia vs spy can occur when considering deferred income versus immediate income strategies. The right choice depends on whether you’re looking for income now, income in the future, liquidity, growth or guarantees.
Why Consider Guaranteed Lifetime Income?
A key benefit of a Single Premium Immediate Annuity is that it provides guaranteed income. It can be used to pay for the essential expenses like housing, utilities, food and medical costs, and not necessarily as a monthly cash-out of investments.
If your life turns out to be much longer than expected, you may be able to get longevity insurance from a Single Premium Immediate Annuity. This is one of the major unknowns of retirement: running out of money.
Part of the pricing of lifetime annuity payments reflects mortality credits. The basic idea is that the insurer gets many premiums from many people, and the economics of the pool can allow the insured longer lives to benefit.
What Should You Consider Before Buying One?
While a Single Premium Immediate Annuity can offer a good source of income, there are also choices to be made. You definitely will have limited access to the original premium after you commit your money to the contract.
Inflation is another consideration. A fixed monthly payment can purchase less in the future should the price increase. It is also important to know about the financial standing of the insurance company, the cash options, death benefits and any riders or fees.
A return of premium rider might be considered when people want to leave assets to their beneficiaries. This can offer extra protection depending on the contract, but it can also offer less income payment initially.
Is a Single Premium Immediate Annuity Right for Your Retirement?
A Single Premium Immediate Annuity might be appropriate if a fixed income is more valuable than having the lump-sum invested. It can be especially helpful in paying bills that must be settled no matter what the market conditions are.
But, don’t have to invest the entirety of your retirement funds in an annuity. Some retirees allocate an annuity to cover essential costs and hold other assets as a buffer for unexpected needs, growth, travel, and/or leaving an inheritance.
The main factor to consider before choosing is to compare the income guarantee, the liquidity of the insurer, the protection against inflation, the provisions for the beneficiaries and the strength of the financial institution.
Conclusion
A Single Premium Immediate Annuity may offer a guaranteed retirement income stream and minimize the risk of running out of money during retirement. This can be helpful to cover basic expenses and offer increased monthly cash flow confidence.
When buying this, the first consideration is to compare it to another insurance policy, like Deferred Income Annuity or Multi Year Guaranteed Annuity, and also carefully read the contract’s payout and death benefit terms.
Frequently Asked Questions
What is a Single Premium Immediate Annuity?
A Single Premium Immediate Annuity is an insurance contract funded with one lump sum that provides scheduled income payments according to the selected payout terms.
How soon does a Single Premium Immediate Annuity pay income?
A Single Premium Immediate Annuity is designed to begin income relatively soon after purchase, although the exact timing depends on the contract and insurer.
What is guaranteed retirement income?
Guaranteed retirement income is income designed to continue according to the terms of a contract, providing greater predictability than relying entirely on market-based withdrawals.
What is guaranteed lifetime income?
Guaranteed lifetime income is income that continues for the annuitant’s lifetime according to the contract. It can help address the risk of outliving retirement savings.
What is annuitization?
Annuitization is the process of converting an annuity’s value into a stream of scheduled payments, such as monthly income for life or for a specified period.
What are mortality credits?
Mortality credits are an important part of how lifetime annuities are priced. The insurer pools risks among policyholders, allowing the economics of the pool to support lifetime payments.
Is SPIA vs MYGA an important comparison?
Yes. SPIA vs MYGA compares two different goals: immediate income from an annuity versus interest accumulation through a multi-year guaranteed product.
What is longevity insurance?
Longevity insurance is designed to provide income later in life or throughout a person’s lifetime, helping protect against the financial risk of living longer than expected.
What is a return of premium rider?
A return of premium rider can provide a beneficiary benefit based on the contract’s terms if the annuitant dies before receiving a specified amount of payments.
Should I use an immediate annuity for essential expenses?
An immediate annuity may be useful for covering essential expenses when predictable income is a priority, but the decision should consider liquidity, inflation, taxes, and your overall retirement plan.